
Property values across Spain's coast have moved sharply since 2024. Málaga province sits near the top of that curve. For UK buyers used to slower, steadier price growth back home, the pace on the Costa del Sol can be genuinely surprising. It is not evenly spread across every address, though, and the differences matter for anyone planning a purchase.
The headline number
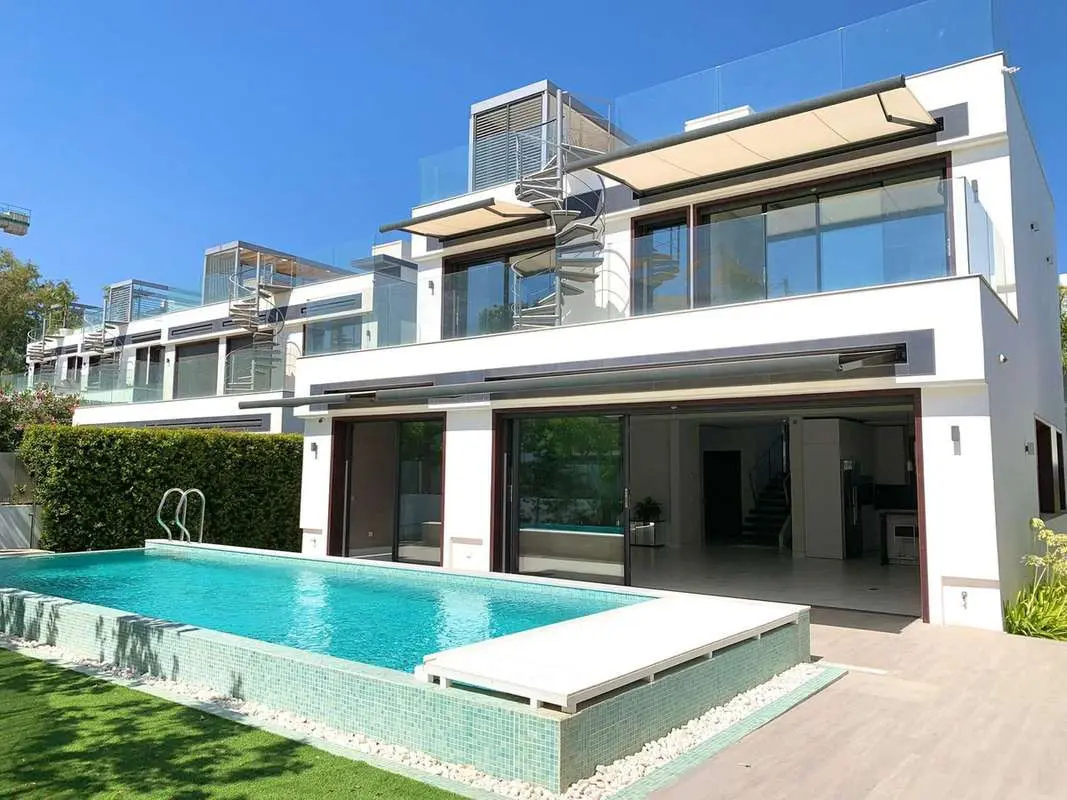
Appraisal data from Tinsa, Spain's leading independent valuation company, shows Málaga city's average price for finished housing climbed 14.70% year-on-year in the second quarter of 2026. That figure covers both new and resale stock. It took the average to €2,932 per square metre. This is one of the sharpest annual increases recorded anywhere in Spain over that period. It has been building steadily too, rather than spiking in a single quarter.
Why Málaga specifically
Several factors are compounding at once here. New-build supply has struggled to keep pace with demand across the whole province, not just the coastal strip. Foreign buyers, UK nationals prominent among them, have kept purchasing through periods when domestic demand softened elsewhere. The Costa del Sol premium that Marbella already commanded has pulled the wider provincial average up with it. It is not sitting as an isolated pocket of high prices any more.
Micro-area divergence
Not every address on the coast is moving at the same pace. Buyers researching property for sale in Nueva Andalucía will find pricing that differs meaningfully from both central Marbella and the western towns further along the coast. Areas closer to golf courses and international schools have generally held their premiums better than more generic apartment stock. Villa supply in particular remains tight relative to demand right now.
New build versus resale
The gap between new-build and resale pricing has narrowed slightly over the past year. It remains wide, though. New developments still command a premium tied to specification, energy efficiency and structural warranties. Resale stock has closed some of that distance, mainly because buyers are competing harder for limited inventory currently on the market.
Financing at higher price points
Non-resident mortgages typically cover a smaller share of the purchase price than a resident buyer would get. The ratio often sits around 60 to 70% of valuation, below what Spanish residents can usually access. As prices climb, the cash gap required upfront becomes more significant in absolute terms. Buyers financing a purchase should factor in Spanish bank valuations too. These do not always match the agreed sale price exactly.
What rising prices mean for rental yield
Higher purchase prices generally compress gross rental yields, since rents have not risen at quite the same pace as capital values over the past year. That does not make the coast a poor rental market. It does mean buyers focused primarily on yield should run the numbers carefully on any specific property. Coast-wide averages are a poor substitute for a property-specific calculation.
The development pipeline ahead
A modest wave of new developments is due to complete across the province over the next two to three years. Most of this pipeline is concentrated around Marbella and its immediate surroundings. That pipeline may ease some of the current supply pressure. Most analysts expect any easing to be gradual rather than sudden, though, given how long large developments take to plan and build in this region.
Who is buying at these prices
Buyer demand at the top of the market remains international rather than domestic. UK, Scandinavian and Northern European buyers continue to account for a large share of transactions above the coast-wide average price. That international mix has historically made prime Costa del Sol stock less sensitive to purely domestic Spanish economic conditions than markets elsewhere in the country.
How this compares with the rest of Spain
Málaga's growth rate has consistently outpaced the national average for finished housing over the past year. Provinces further from major coastal demand, particularly inland and northern regions, have generally recorded steadier, more modest increases by comparison. That gap is one reason buyers researching the Costa del Sol from abroad are sometimes surprised by how fast the market has moved since their last visit. Prices that felt high eighteen months ago often look like the entry point for a given area today.
What this means for buyers
For buyers weighing up when to act, the honest answer is that waiting for a correction has not paid off over the past two years. Crinoa's villa listings in Marbella reflect a market where well-located stock rarely sits unsold for long. Pricing has moved up steadily, rather than in short bursts that might reverse quickly. That does not mean every property is fairly priced. It does mean broad market timing has mattered less than area and property selection.
Costs at today's prices
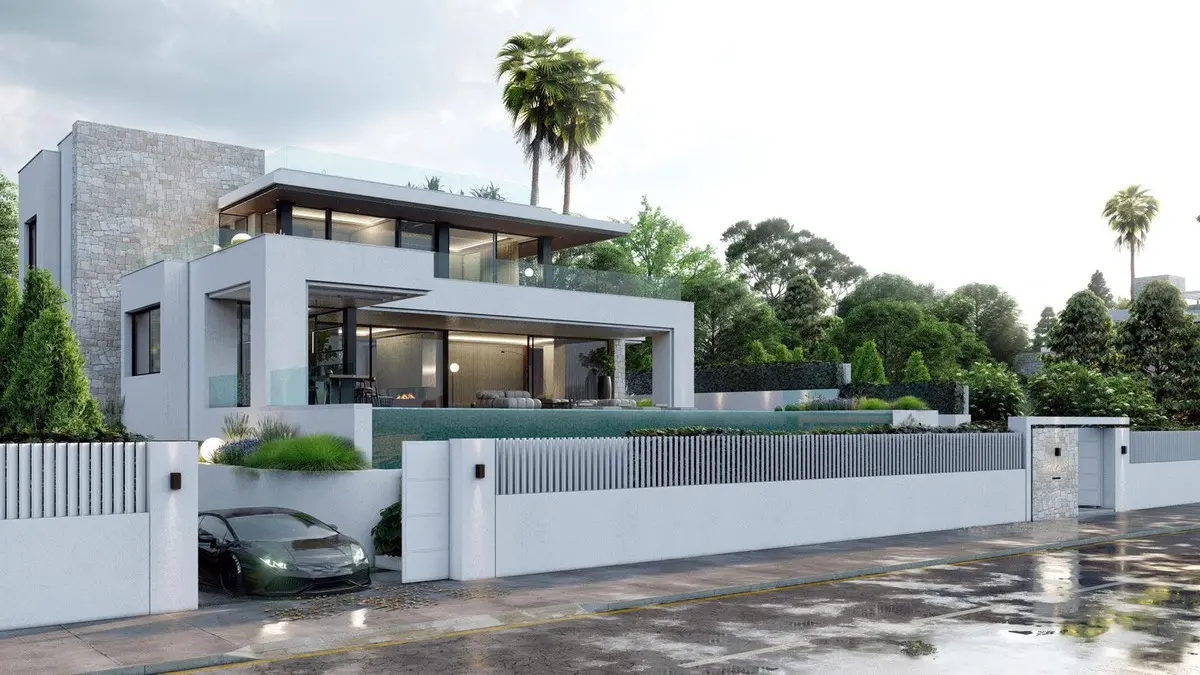
Higher property values also mean higher absolute purchase costs. Non-resident buyers should still budget roughly 8% of the purchase price for transfer tax, notary fees, registry costs and legal fees combined. That percentage now applies to a larger base figure than it did two years ago. On a €1.5 million purchase, that works out at around €120,000 in additional costs. It is a number worth confirming with a lawyer before making an offer.
The bottom line
Málaga province's price growth is not a short-term spike. It reflects sustained demand meeting genuinely limited supply, concentrated most heavily around Marbella and its immediate surroundings. For UK buyers, the practical takeaway is straightforward. The areas that already commanded a premium are generally the ones holding and extending it, rather than the market correcting towards cheaper stock further inland.